 By
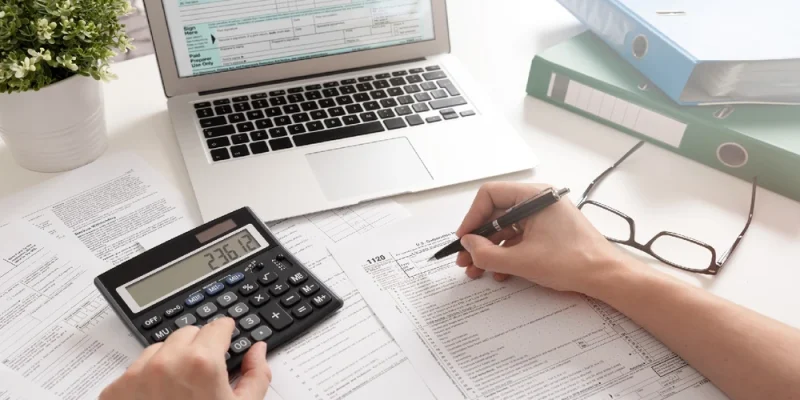
Bookkeeping services help small businesses keep financial records organized and current. The right arrangement gives owners clearer information about income, expenses, cash, and outstanding balances, while making it easier to prepare reports and work with a tax professional.
What bookkeeping services include
Bookkeeping commonly includes recording transactions, categorizing income and expenses, reconciling bank and credit-card accounts, tracking accounts receivable and payable, and preparing routine financial reports. Depending on the provider and agreement, services may also include invoicing, payroll coordination, expense management, or month-end close support. Bookkeeping is not automatically the same as tax preparation, audit, or strategic financial advice. Define the scope before hiring so you know which responsibilities remain with you or another professional. Decide who approves bills, vendor changes, refunds, and bank transfers. Bookkeeping providers may record or prepare transactions, but approval and payment authority should be clearly controlled by the business owner or designated staff.
Signs a business may need help
Owners may consider outsourcing when records are consistently behind, transactions are difficult to reconcile, invoices go unpaid, or financial reports arrive too late to guide decisions. Growth can increase complexity through additional staff, payment systems, inventory, or multiple sales channels. A business may also need support when the owner spends more time on administration than on customer work. Hiring help should solve a defined problem and improve the reliability or timeliness of records, not simply move an unclear process to another person. At onboarding, reconcile opening balances and agree on how historical errors will be corrected. Unclear starting balances can cause recurring differences and undermine confidence in every later report.
Compare in-house and outsourced options
An in-house bookkeeper offers direct availability and may understand daily operations closely, but salary, training, software, and backup coverage add cost. An outsourced provider can offer flexible service levels and access to established processes, although communication and access must be managed carefully. Software-assisted or hybrid models may suit very small businesses with simple transactions. Compare total cost, service scope, responsiveness, security, and continuity rather than comparing hourly rates alone. Decide who approves bills, vendor changes, refunds, and bank transfers. Bookkeeping providers may record or prepare transactions, but approval and payment authority should be clearly controlled by the business owner or designated staff.
Check experience with your business model
A provider familiar with your industry may understand common transaction types, inventory needs, project costing, payment platforms, or billing cycles. Ask about businesses of similar size and complexity, and request an explanation of how they would handle your workflow. Industry experience is useful but does not replace professional competence or clear controls. For complex matters, confirm which tasks require a licensed accountant, tax adviser, or other qualified professional in your jurisdiction. At onboarding, reconcile opening balances and agree on how historical errors will be corrected. Unclear starting balances can cause recurring differences and undermine confidence in every later report.
Understand the monthly workflow
Agree on how documents will be collected, who categorizes unusual transactions, when bank accounts will be reconciled, and when reports will be delivered. Set deadlines for submitting receipts, approving bills, and answering questions. Clarify how the provider handles missing documents, duplicate transactions, refunds, loans, owner contributions, and large purchases. A predictable close process helps the owner understand when the books are complete and which items remain unresolved. Decide who approves bills, vendor changes, refunds, and bank transfers. Bookkeeping providers may record or prepare transactions, but approval and payment authority should be clearly controlled by the business owner or designated staff.
Review reports that support decisions
Common reports include the profit and loss statement, balance sheet, cash-flow information, accounts receivable aging, and accounts payable summary. The most useful report depends on the business model and the owner’s decisions. Ask the provider to explain how often each report will be prepared and what assumptions or limitations apply. Reports are only as useful as the underlying records, so reconciliation and consistent categorization matter. Review results against budget and prior periods rather than looking only at a single month. At onboarding, reconcile opening balances and agree on how historical errors will be corrected. Unclear starting balances can cause recurring differences and undermine confidence in every later report.
Ask about software and data security
Confirm which accounting platform will be used, who owns the account, and how access is granted when the relationship ends. Use individual logins, multi-factor authentication where available, and least-privilege access. Agree on secure document transfer, backup practices, and the handling of payroll, bank, and customer information. Avoid sending passwords in plain text or giving a provider unnecessary authority to move funds. The business should retain control of its records and have a practical way to export them. Decide who approves bills, vendor changes, refunds, and bank transfers. Bookkeeping providers may record or prepare transactions, but approval and payment authority should be clearly controlled by the business owner or designated staff.
Compare fees and service boundaries
Providers may charge a fixed monthly fee, hourly rate, transaction-based fee, or separate price for add-on work. Ask what volume is included, how extra transactions are billed, and whether cleanup of prior periods costs more. Confirm whether payroll, sales tax filings, year-end preparation, inventory accounting, or management reporting is included. A low monthly price may exclude tasks you assumed were covered. Get the scope, delivery schedule, communication expectations, and termination process in writing. At onboarding, reconcile opening balances and agree on how historical errors will be corrected. Unclear starting balances can cause recurring differences and undermine confidence in every later report.
Keep owner oversight in place
Outsourcing bookkeeping does not remove the owner’s responsibility to review the business’s finances. Check bank reconciliations, unusual transactions, overdue receivables, cash needs, and reports on a regular schedule. Separate the ability to record transactions from the authority to approve payments where practical. Ask questions when a result changes unexpectedly. The U.S. Small Business Administration’s finance guidance provides a general starting point for understanding financial management. Decide who approves bills, vendor changes, refunds, and bank transfers. Bookkeeping providers may record or prepare transactions, but approval and payment authority should be clearly controlled by the business owner or designated staff.
Choose a provider with a clear process
Before signing, ask for a sample report, onboarding checklist, response-time expectations, reference process, and explanation of how errors are corrected. Start with a defined transition plan and reconcile opening balances carefully. Reassess after the first few month-end closes: are the books current, are reports understandable, and are questions resolved promptly? Good bookkeeping services create dependable records that help the business make decisions, meet obligations, and collaborate more effectively with tax and financial professionals. At onboarding, reconcile opening balances and agree on how historical errors will be corrected. Unclear starting balances can cause recurring differences and undermine confidence in every later report.
Conclusion
Choose bookkeeping support based on accurate records, clear responsibilities, secure systems, and useful reporting. Regular owner review and a well-defined month-end process help turn bookkeeping into a practical management resource.
[…] estimates often miss small but recurring expenses such as software, payment fees, shipping, returns, maintenance, insurance, taxes, and professional […]
[…] will gain automatic access to it. Therefore, it is best to have things clarified before you sign your agreement so that you know what exactly you are getting into and what exactly you are getting for the money […]